Strengths
- The best-performing precious metal for the week was gold, but it was still down 0.68%. Australia’s Federal Court ruled that the August 2024 declaration affecting Regis Resources’ delayed McPhillamys Gold Project in New South Wales was legally invalid, potentially removing a key regulatory obstacle to development. RBC values the project at A$1.00 per share, representing approximately 14% of its estimated group net asset value of A$7.10 per share.
- Aya Gold & Silver produced approximately 2.03 million ounces of silver in the third quarter (Q3), up 51% year-over-year (YoY) and exceeding BMO’s estimate of 1.62 million ounces. Boumadine’s historical tailings reclamation operation contributed 537,000 ounces, well above the 232,000-ounce forecast, while Zgounder achieved record throughput of 4,096 metric tons per day, up 5% quarter-over-quarter.
- Mineros increased its full-year production guidance to 235,000–245,000 ounces, up from 220,000–240,000 ounces, after Q3 gold output rose 14% YoY to 62,565 ounces, according to Bloomberg.
Weaknesses
- The worst-performing precious metal for the week was silver, down 6.43%. Buenaventura reduced its full-year direct gold production forecast to 112,000–131,000 ounces from 120,000–139,000 ounces and lowered its silver production outlook to 14.4–15.8 million ounces from 14.7–16.1 million ounces, according to Bloomberg. The revisions point to weaker-than-expected production across both metals.
- Evolution Mining reported fiscal first-quarter (Q1) 2027 gold production of 154,000 ounces, approximately 6% below RBC’s consensus estimate of 163,000 ounces. The shortfall was primarily driven by power outages and planned mill shutdowns at Red Lake, along with unplanned power interruptions at Mungari that limited mill availability.
- Wesdome Gold Mines reported consolidated gold production of 41,300 ounces in the third quarter (Q3), below expectations due to lower-than-anticipated grades at both operations and reduced throughput at Kiena, according to RBC. Full-year guidance remains unchanged at 180,000–205,000 ounces, but production is expected to finish below the midpoint. Meeting guidance will require Q4 production of 50,000–62,000 ounces, supported by higher throughput at Eagle River, the continued Presqu’île ramp-up and operational improvements at Kiena Deep.
Opportunities
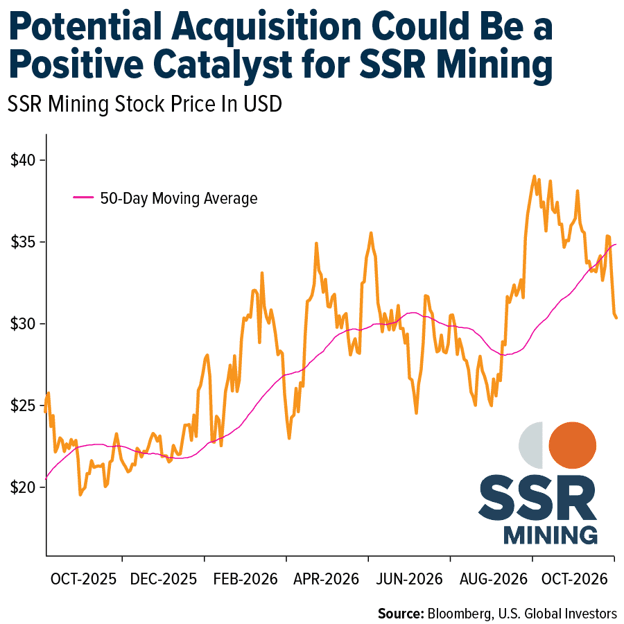
- SSR Mining agreed to acquire Roxmore Resources for C$6.75 per share in cash, with Roxmore shareholders also receiving shares in a new spin-off company. The acquisition would add the Converse Gold Project, located just 6 kilometers from SSR’s Marigold Complex. Meanwhile, Marigold’s updated 20-year mine plan targets 3.3 million ounces of gold production, with reserves increasing 43% to 4.63 million ounces and an estimated after-tax NPV of $3.3 billion at consensus gold prices.
- Bolivia issued a decree eliminating the requirement for central bank authorization of gold exports. Under the new rule, exporters must demonstrate that 80% of export proceeds are deposited in domestic financial institutions. The reform aims to facilitate private gold exports, reduce administrative barriers and increase foreign currency inflows into the country’s financial system, according to Bloomberg.
- Goldman Sachs analysts highlighted that central bank reserve diversification, fiscal sustainability concerns and sanctions risks continue to reinforce gold’s role as a hedge against currency debasement and declining institutional credibility. Meanwhile, major gold miners collectively hold approximately $20 billion in cash, providing financial flexibility for potential acquisitions, capital investment and shareholder returns despite the recent decline in gold prices.
Threats
- Bank of America warns that gold’s recent weakness despite rising ETF holdings could signal further downside if investors begin selling. Softer purchases from central banks, China and India have also weighed on demand. Meanwhile, gold fell as much as 2.1% to approximately $4,070 per ounce after U.S. consumer prices rose 0.6% month-over-month in September, reigniting concerns about further Federal Reserve tightening. Gold recovered about $110 per ounce by Friday. BofA expects gold to average $4,000 per ounce in Q4 2026 before recovering to $4,813 in 2027.
- UBS expects gold mining companies to face sustained operating cost pressures, with unit costs likely to rise further into 2027, potentially exceeding current consensus estimates. The bank also anticipates additional M&A activity but favors large-cap producers that prioritize sustainable cash returns over acquisitions, highlighting potential risks associated with deal execution and capital allocation.
- According to Morgan Stanley, gold has declined approximately 10% from its August peak but remains above $4,000 per ounce. Based on the historical relationship between gold and real yields observed from March through July, prices would have fallen below $3,000 per ounce, approximately 28% below current levels. However, central bank purchases and ETF inflows have helped offset these macroeconomic pressures, suggesting gold is becoming less sensitive to higher real yields.
