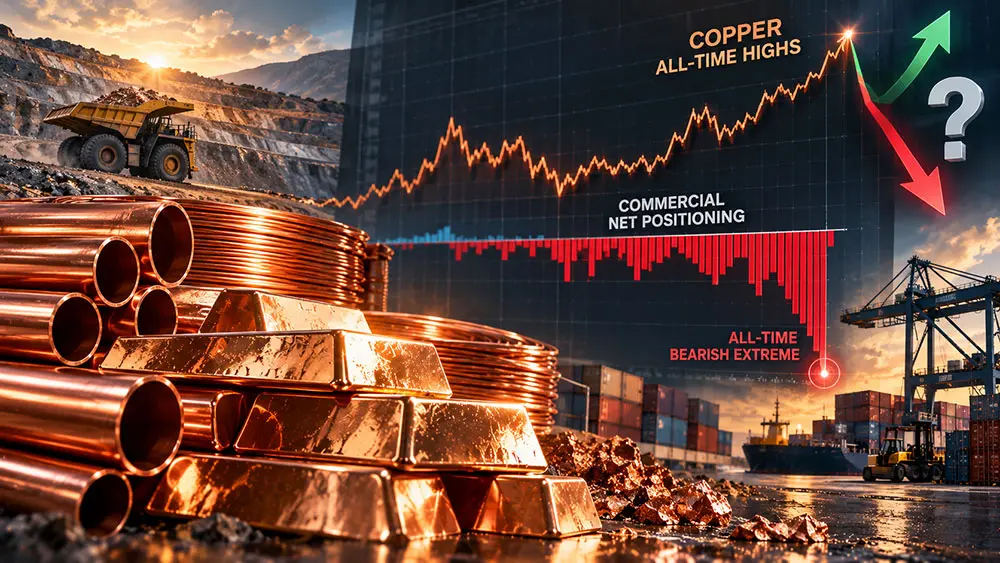
Copper is one of the most closely watched industrial metals, and right now it's sending a positioning signal that deserves careful attention. According to the latest Commitments of Traders report, copper has reached an all-time bearish COT extreme in the Commercials category. That is a historically unusual reading — one that raises real questions about what comes next, while also introducing a scenario that complicates a straightforward bearish interpretation.
Let me walk through both sides of this.
An All-Time Extreme in Commercial Positioning
Commercials in the futures market are the hedgers — producers, processors, and end users who use futures primarily to manage price risk rather than to speculate. When their net short positioning reaches an extreme, the conventional COT interpretation is that they are heavily hedged against further price rises, which historically has often coincided with price peaks or periods of price weakness.
On the all-time chart for copper — data going back to 1990 — Commercial positioning has now reached an extreme that has not been seen before in the full history of this dataset. That is a significant data point. It does not, by itself, tell us that copper prices must fall. But it does place current positioning in historically unusual territory, and that makes the market worth watching closely.
The Complicating Factor: Commercial Capitulation
Here is where the picture becomes less straightforward. Copper prices are currently at all-time highs — at least over the period covered by this dataset, going back to 1990. That combination — an all-time bearish COT extreme in Commercials alongside all-time price highs — introduces a scenario that I think is worth considering seriously: commercial capitulation.
Commercial capitulation is not a guaranteed outcome, and I want to be clear that it remains a possibility rather than a confirmed development. But the mechanics are worth understanding. If Commercials are holding large short positions and the market continues to rise, they can face mounting losses on those positions. At some point, they may be forced to close them — which means buying, because closing a short requires purchasing the contract. That buying pressure, if it materializes, would add further fuel to the rally rather than causing the reversal that a bearish COT extreme might typically suggest.
We saw something comparable in 2020. At that time, copper was also at what was then an all-time bearish extreme in Commercial positioning — yet the market continued to move higher rather than reversing. The current situation has echoes of that episode, though the starting price level is considerably higher now.
So the question on the table is this: will the all-time bearish extreme eventually exert downward pressure on copper prices, or will rising prices force Commercials to cover shorts and inadvertently extend the rally? I do not think the data resolves that question definitively at this point. Both scenarios are plausible, and positioning alone cannot tell us which one will play out.
Mixed Signals Worth Noting
Looking at the short-term picture for copper adds another layer. On a one-year chart, the most recent change in Commercial net positioning is actually bullish — meaning Commercials have been reducing net shorts or increasing net longs in the most recent reporting period. On the COTbase change analysis framework, this qualifies as a bullish COT change signal.
That creates a genuinely mixed picture: a bullish short-term change signal sitting inside an all-time bearish long-term extreme. These are not contradictory — they operate on different timeframes and measure different things. But it does mean traders should be cautious about drawing a single clean conclusion from copper's COT data right now. The short-term and long-term signals are pulling in different directions, and the price context adds further complexity.
What This Means for Copper Watchers
Copper's COT setup is one of the more analytically interesting situations in the current report precisely because it does not resolve neatly. The all-time bearish extreme in Commercial positioning is a real and historically unusual reading. In many past instances, that kind of extreme has been associated with price weakness over the weeks and months that followed. But the presence of all-time price highs and the real possibility of forced short-covering means the bearish case is not as clean as the headline extreme might suggest.
I am watching this market carefully. The positioning is extreme enough to take seriously. But I would want to see price behavior and subsequent COT reports begin to confirm a directional move before treating this as a resolved signal. For now, copper sits at an unusual intersection of historic positioning and historic price levels — and that combination warrants attention without demanding a firm conclusion.
Watch the full COT analysis for Report 41 of 2026, including the chart walkthroughs, the new charting tools and ICOT score detail, at https://www.youtube.com/watch?v=UMrWjrrADE4
