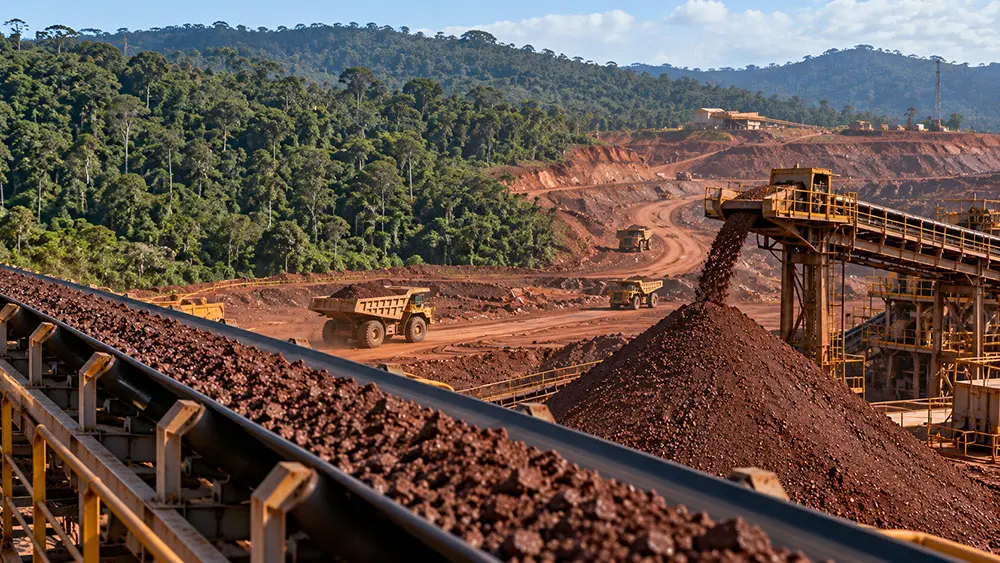
Brazilian miner Vale (NYSE: VALE) on Thursday booked a 20% slump in third-quarter core profit, battered by lower iron ore prices and elevated fuel and freight costs.
While the decline in pro forma adjusted earnings before interest, taxes, depreciation and amortization (EBITDA) to $3.51 billion was in line with expectations, iron output for the quarter fell short.
A lower supply of run-of-mine — unprocessed ore mined from a pit — at Vale’s Serra Norte complex in Brazil, contributed to a 6% decline to 88.4 million metric tons, below a Visible Alpha consensus of 90.1 million tons.
Vale, one of the largest iron ore producers in the world, said, however, that it was confident that it would reach the lower end of its 2026 iron ore output projection of between 335 million tons and 345 million tons.
The company also said it resumed operations at its Brazilian Fabrica mine in September. The mine had been halted since the beginning of the year after a water overflow caused damage to the environment.
Iron ore prices have fallen in recent months on expectations of lower demand from main consumer China and solid supply from major producers. The average realized price of iron ore fines came in at $85 per ton, a 10% decline.
Total costs for iron ore fines jumped 23%, driven in large part by higher diesel and bunker fuel as well as freight costs that climbed in the wake of the US-Israeli war on Iran.
One bright sign was a 2% rise in net revenue to $10.6 billion, compared to a Visible Alpha consensus of $10.4 billion. That was helped by gains for its copper and nickel businesses, while sales of steelmaking material held steady on drawdowns of inventories.
Vale said it expects to deliver 2026 production for copper and nickel near the upper end of their yearly projected ranges.
(Reporting by Andre Romani in Sao Paulo; Editing by Fernando Cardoso and Edwina Gibbs)
