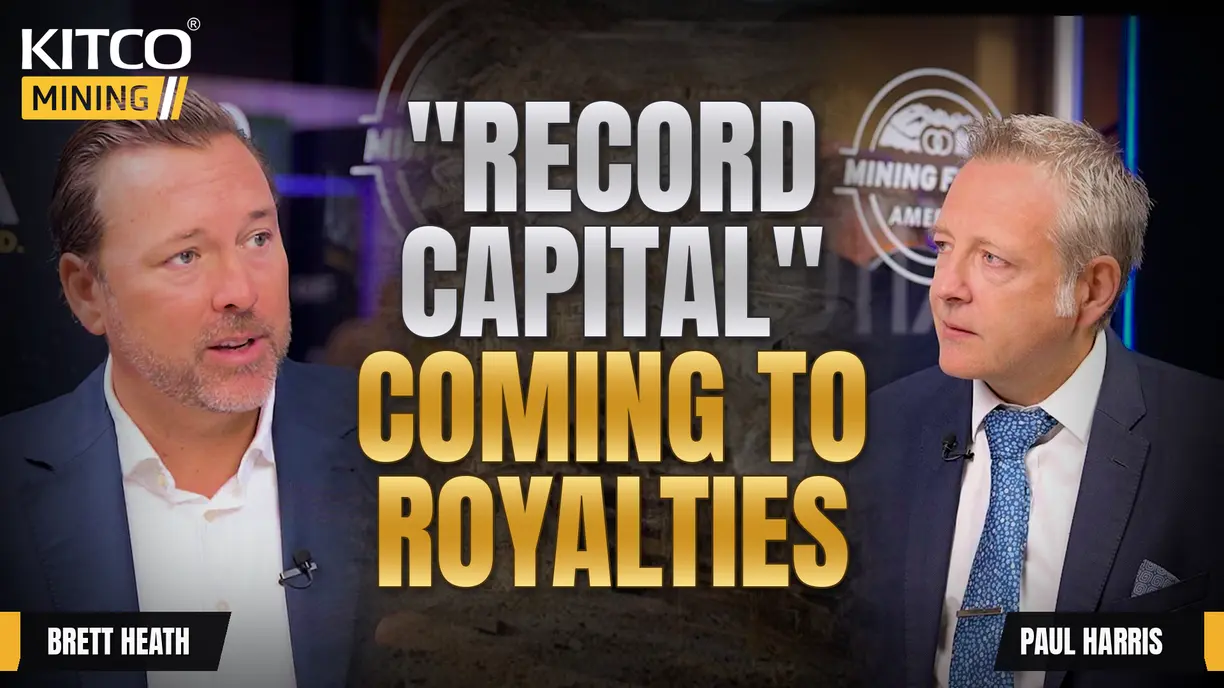
(Kitco News) Metalla Royalty & Streaming CEO Brett Heath says the way mines get financed is changing, with royalty and streaming money taking on a role it has never held before.
“What we’re seeing today is what I’ve never seen in my career, which is you’re seeing streams start to become basically a mainstream form of financing,” Heath told Kitco Mining on Sept. 28 at the 2026 Mining Forum Americas in Colorado Springs. “So stream and royalties have always been an alternative form of financing.”
“But that has changed, and I think it’s being driven by really the long end of the curve,” he said. As long-term yields and the rates on credit facilities rise, Heath expects royalty and stream financing “is going to become kind of the critical part of that capital stack where everything else is built around.”
The miners taking that money look different now too. “In the past, it was always because they were trying to fix their balance sheets, but now with metal prices where they are, they’re kicking off unlimited free cash,” he said. The appeal, in his view, is that a stream is tied to the ore body rather than to interest rates. “They don’t move. They only become more expensive as the price goes up and obviously the mining company makes money alongside.”
Copper is where the numbers are largest. “These are not $1 billion type of builds. They’re four, five, six, seven, $8 billion builds,” Heath said. A stream sized for one of those projects could reach “two, three, $4 billion deals,” he said, and “over the next year or two and three, we are going to see record capital deployed by the royalty and streaming sector. I think it’s all in front of us. We’re just at the start of it right now.”
Deals that size may be split among several buyers. “I think we will see syndication within the royalty sector. These are very, very big deals. And they’re very, very large checks.”
At Metalla, Heath credits its improving results to a portfolio built years ago that is now starting to pay. “So what’s driving that step change is just the portfolio maturing,” he said. The company’s approach “is really the arbitrage of time combined with world-class geology.” Metalla reported record second-quarter results in August and expects 3,500 to 4,500 attributable gold equivalent ounces in 2026. “We’re a profitable company. We’re showing net income. It’s just growing from there.”
The clearest example is Metalla’s 1.5% net smelter return royalty, which covers all of IAMGOLD’s Gosselin deposit and a small part of the Côté gold mine in Ontario. “We paid about $6 million for that when we acquired it. Today, the present value of that royalty, analysts carry it at around $120 million US,” Heath said of the original interest, bought about five years ago. Metalla added the final 0.15% for C$3.4 million in October 2025.
Gosselin is the growth story. “Gosselin is a deposit that’s gone from zero to over eight million ounces in five years,” Heath said. IAMGOLD is expected to release a technical study integrating it into the Côté mine plan before the end of 2026.
Tether, the stablecoin issuer, has built a stake of about 14% in Metalla through market purchases. “I can’t comment on what my shareholders’ objectives are,” Heath said. “But it’s great to see disruptive capital come into the sector. Obviously, Tether has a very large balance sheet.”
A bigger shareholder base gives Metalla room for larger deals, but Heath said size alone is not the goal. “We are not going to grow for the sake of growth,” he said. “We don’t necessarily buy into bigger is always better.”
Watch the full video on the Kitco Mining YouTube channel.
This article/video was produced with support from a Kitco sponsor. The views expressed in this content do not necessarily reflect the views of Kitco Metals Inc. Kitco does not endorse or recommend any company, security, investment product, or investment strategy. This content is for informational purposes only and should not be considered investment advice.
Learn more about Metalla Royalty & Streaming here