(Kitco Commentary) - When the price of Gold falls, confidence is questioned but when Gold rises investors are said to be seeking safety. Those explanations can be useful, but they leave a considerable amount of the physical market out of the picture.
A price chart records the outcome of trading. It does not tell us why a household has decided to own gold, whether an existing holder intends to sell, or how easily a buyer can obtain the particular coins or bars they want. For anyone trying to understand physical investment demand, those distinctions matter. The question is not simply whether gold is going up or down, it is what people are doing in response, and why.
Different parts of the market can tell different stories
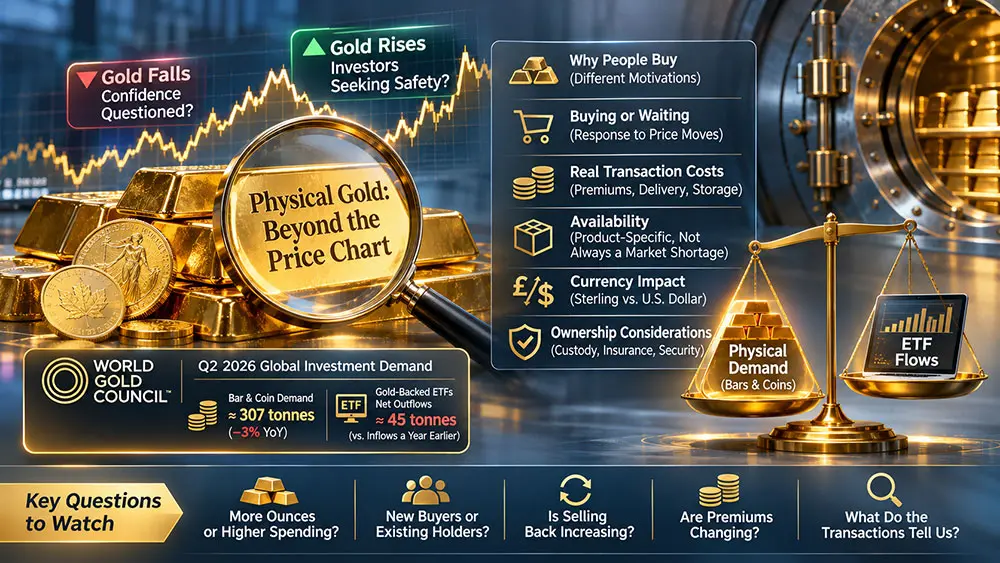
World Gold Council figures for the second quarter of 2026 provide a useful example. Global bar and coin demand was approximately 307 tonnes, down 3% compared with the same quarter a year earlier. Gold-backed ETFs, meanwhile, recorded net outflows of approximately 45 tonnes, compared with substantial inflows a year earlier.[1]
Those figures describe different forms of investment behaving differently. They also come with an important qualification which is that bar and coin buying had fallen sharply from an exceptionally strong first quarter.
The reasonable conclusion is neither that physical buyers were abandoning gold nor that they were ignoring the correction. It is that the composition and starting point of demand matter. A single investment-demand headline can obscure both.
Physical ownership also covers different motivations. A buyer seeking a short-term gain, someone diversifying accumulated savings and a parent purchasing coins for a future gift may all complete the same transaction. Their reasons for doing so, and their likely responses to volatility, can differ considerably.
A lower price can prompt buying or hesitation
It is tempting to assume that cheaper gold automatically attracts more physical buyers. In practice, the interpretation of the fall matters.
Someone who has already decided to build a holding may see a lower price as an opportunity. Someone still deciding whether gold belongs in their savings may regard the same movement as a reason to wait.
The World Gold Council’s second-quarter commentary described precisely that complexity: short-lived bargain hunting in the United States, but greater caution among European retail investors following the correction.[1]
That is why an enquiry is not the same as a purchase, and a purchase is not necessarily evidence of lasting conviction. To assess physical demand properly, we need to examine completed transactions, repeat buying and selling back, alongside the reasons customers give for their decisions.
Turnover alone is another imperfect measure. When prices rise, the same cash commitment buys less metal. A business can report higher sales revenue without selling more ounces. Equally, increased transaction numbers can reflect smaller purchases rather than greater overall demand.
The price on the screen is not the whole transaction
Physical buyers purchase a product, not an abstract spot quotation. Their cost includes the premium attached to a particular coin or bar and, where applicable, delivery or storage. Their eventual proceeds depend on the price offered when they sell. The difference between purchase and resale terms matters, particularly over shorter holding periods.
Availability matters too. A delay affecting one popular product does not, by itself, demonstrate a shortage across the gold market. It could reflect demand for that specific item, minting capacity, distribution or a dealer’s stock position.
The reverse is also true which is the fact a subdued headline price does not tell us whether a particular product is readily available at its usual premium.
Dealer commentary is most useful when it makes these distinctions explicit. “Demand is strong” means more when accompanied by the period being measured, the products involved and whether the evidence concerns enquiries, orders or metal delivered.
Sterling changes the picture
For UK buyers, the dollar gold price is only part of the calculation.
A weakening pound can cushion a decline in dollar gold prices, while a strengthening pound can reduce the sterling benefit of a dollar rally. Two investors reading the same international headline may therefore be experiencing different returns.
That makes currency an essential part of any discussion with a British physical buyer. The relevant starting point is the sterling cost of acquiring the holding and the sterling proceeds available on sale, including transaction costs.
Ownership brings another set of questions
Beyond price, a physical purchase requires decisions about possession, custody, insurance and eventual sale.
A buyer needs to understand what they own, where it will be held, the terms of any storage arrangement and how they can access or sell it. These questions deserve attention alongside the market outlook.
Physical gold carries risks and costs. It produces no income, its price can fall, and storage or insurance can reduce returns. Direct possession also brings security responsibilities. Explaining those practicalities is part of making a credible case for ownership.
What we should watch
The physical market becomes more informative when we look beyond the day’s percentage move.
Are customers buying more ounces or simply spending more because prices are higher? Are purchases coming from new buyers or existing holders adding to their positions? Is selling back increasing? Are premiums changing across the market or only for particular products?
An individual dealer’s experience can help answer those questions, but it remains one view of one customer base. It should be identified as such and tested against broader evidence.
For me, that is where commentary from the physical market can add value: explaining the decisions behind the transactions, with enough detail for readers to judge what they mean.
The gold price deserves attention but understanding physical buyers requires a closer look.
