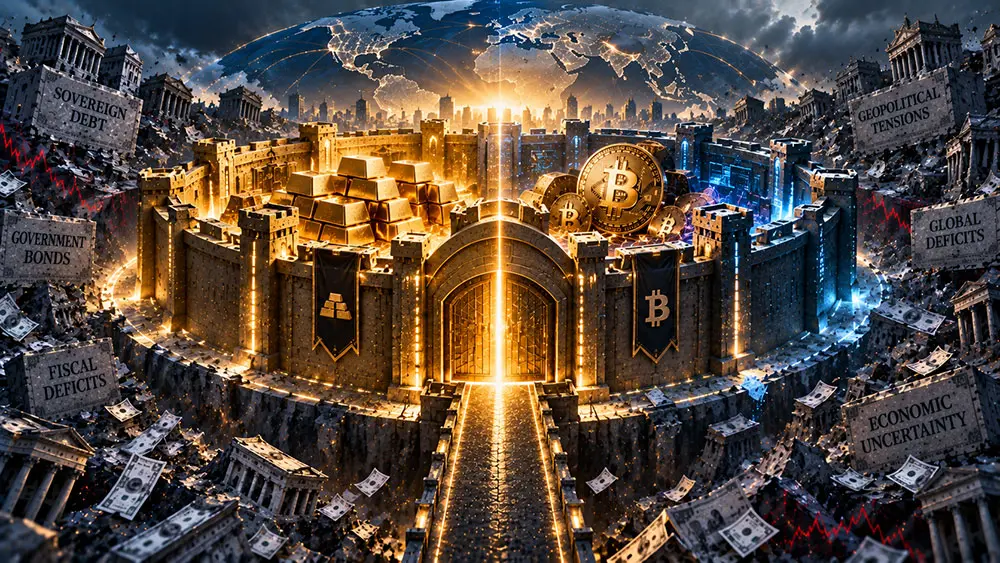
(Kitco News) - Persistent fiscal deficits, ballooning sovereign debt and rising geopolitical fragmentation are forcing investors to rethink what constitutes a safe-haven asset, and one digital asset executive says the answer increasingly includes both gold and Bitcoin.
In an exclusive commentary for Kitco News, Tommaso Mancuso, President and Chief Investment Officer at global digital asset investment manager 3iQ, said the long-running debate over whether Bitcoin can replace gold has become outdated. Instead, institutional investors should view the two assets as complementary components of a broader hard-asset allocation.
Mancuso noted that central banks accumulated an average of roughly 1,000 tonnes of gold annually between 2022 and 2025, about twice the average pace of the previous decade. At the same time, Bitcoin has moved deeper into mainstream finance through spot exchange-traded funds, corporate treasury adoption and increased institutional participation.
The common denominator, according to Mancuso, is growing concern about the sustainability of traditional sovereign assets. In recent weeks, fears over an unsustainable rise in global sovereign debt have pushed gold prices back above $4,300 an ounce, while Bitcoin is currently trading above $75,000 per token.
Mancuso explained that developed economies are facing structurally higher debt burdens and persistent fiscal deficits. Citing International Monetary Fund projections, Mancuso said average government debt among G7 economies is expected to reach 123.7% of GDP in 2026. At the same time, geopolitical tensions are increasing demand for reserve diversification and drawing more attention to sovereign counterparty risk.
“This environment has accelerated the flight toward assets outside traditional sovereign liabilities,” Mancuso wrote.
While Bitcoin is increasingly being considered within the same conversation, Mancuso said gold continues to occupy a unique position as a mature global monetary asset.
“Gold has historically fulfilled this role as a reserve asset during periods of monetary instability, but Bitcoin is increasingly viewed through a similar lens,” he said.
Mancuso pointed out that gold and Bitcoin share what he described as similar “monetary DNA.” Both have constrained supplies, can be owned outside the traditional sovereign financial system and derive a significant portion of their value from their perceived ability to preserve purchasing power rather than from their industrial or transactional utility.
However, he said those similarities mask important differences in how investors should use the two assets.
He pointed out that gold’s monetary network has developed over centuries and is supported by central banks and other institutional investors. Sovereign institutions alone hold more than 36,000 tonnes of physical gold, valued in the report at close to $5 trillion.
“Gold operates primarily as a defensive portfolio anchor,” Mancuso said. “It serves as a reliable ballast against systemic shocks and currency debasement.”
According to the report, gold has historically exhibited annualized volatility of around 12% to 15%, with drawdowns rarely exceeding 30% in modern market regimes. Bitcoin, by comparison, has typically experienced annualized volatility between 40% and 50%, along with historical drawdowns of between 70% and 80%.
Mancuso said that difference means Bitcoin should not simply be considered a digital substitute for gold. Instead, Bitcoin represents a potentially higher-growth and substantially more volatile monetary network, while gold provides stability and liquidity within a hard-asset allocation.
“Gold offers deep, liquid stability to the hard-asset sleeve of a portfolio,” he said. “Bitcoin, by contrast, operates as a high-convexity vehicle with asymmetric upside potential if network expansion continues.”
At the same time, Mancuso said technology is beginning to eliminate some of gold’s traditional disadvantages compared with digital assets.
Tokenized gold products such as Tether Gold and Pax Gold allow investors to retain exposure to physical, vault-secured bullion while taking advantage of blockchain settlement, including 24-hour trading, fractional ownership and the ability to use tokenized bullion as collateral.
The report said the tokenized gold market surpassed $6 billion in early 2026. Although that remains a fraction of the roughly $30 trillion above-ground gold market cited by 3iQ, Mancuso argued that its growth demonstrates how the ancient monetary asset is increasingly adopting infrastructure originally developed for cryptocurrencies.
That development could also address one of gold’s most persistent criticisms: unlike bonds or dividend-paying equities, bullion generates no income and carries storage and insurance costs.
Mancuso noted that tokenized gold can potentially be deployed in lending markets or used as collateral, allowing investors to generate returns while retaining exposure to the metal. However, he cautioned that those returns are not inherent to gold itself and introduce additional smart-contract, counterparty and liquidity risks that physical bullion does not carry.
Ultimately, Mancuso said investors may be asking the wrong question when they debate whether gold or Bitcoin will emerge as the dominant alternative monetary asset.
For portfolio managers, he described gold as the “defensive anchor,” providing a deeply liquid strategic reserve against geopolitical shocks and monetary stress. Bitcoin, meanwhile, represents a “convex growth engine,” offering higher-risk exposure to the continued expansion of an emerging monetary network.
With sovereign debt continuing to rise and confidence in traditional fiscal frameworks facing greater scrutiny, Mancuso said both assets could have increasingly important—but distinctly different—roles in institutional portfolios.
“Gold offers the stability and liquidity of a mature monetary asset, while Bitcoin provides exposure to a monetary network that continues to institutionalise through expanding market infrastructure and growing institutional participation,” he wrote.
See live precious metals prices for gold, silver, platinum and palladium — in USD, CAD and 12 more currencies.
