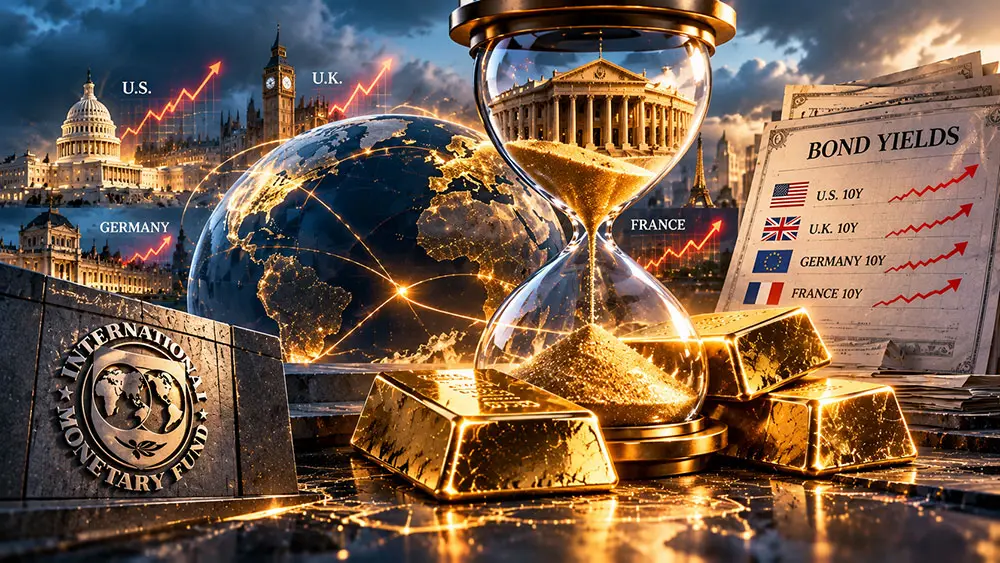
(Kitco News) - If rising bond yields around the world aren’t really a problem, why is the International Monetary Fund talking about them?
The IMF said Thursday that global bond markets continue to function in an “orderly manner,” but this reassurance comes as yields have risen across advanced and emerging economies.
According to Reuters, U.S. 10-year bond yields saw their biggest quarterly rise this century during the third quarter.
Traditionally, higher bond yields are bad news for the precious metal. Gold doesn’t pay interest, so when investors can earn more by holding government debt, the opportunity cost of owning bullion rises.
But that relationship becomes more complicated when yields are rising because investors are demanding greater compensation to hold government debt.
And this is no longer just an American story.
Term premia have risen across major developed markets, including the U.K., France and Germany, as investors confront persistent inflation, growing government borrowing requirements and deteriorating fiscal balances.
In other words, government bond markets may still be functioning perfectly well, but investors are demanding a higher price for the risks they are taking.
That could prove increasingly important for gold.
Gold has already demonstrated remarkable resilience in an environment that, according to the traditional playbook, should have crushed demand. U.S. Treasury yields have risen to levels not seen since 2002, monetary policy has tightened and the U.S. dollar has strengthened. Yet gold remains above $4,000 an ounce.
Real yields at 2.24% present a genuine headwind for gold. But that doesn’t diminish the precious metal’s role as a monetary asset. Gold has no sovereign issuer, no fiscal deficit and no refinancing requirements. It doesn’t depend on a government continually issuing larger amounts of debt to meet its obligations.
The IMF explicitly says markets remain orderly. But analysts have noted that orderly doesn’t necessarily mean risk-free. The important question is whether rising global yields represent attractive competition for gold or a growing risk premium attached to sovereign debt.
If it is increasingly the latter, higher yields may not be as bearish for gold as conventional wisdom suggests.
Gold doesn’t need the global bond market to break.
It may only need investors to start questioning how reliable that market will remain as governments issue ever more debt at increasingly expensive interest rates.
See live precious metals prices for gold, silver, platinum and palladium — in USD, CAD and 12 more currencies.