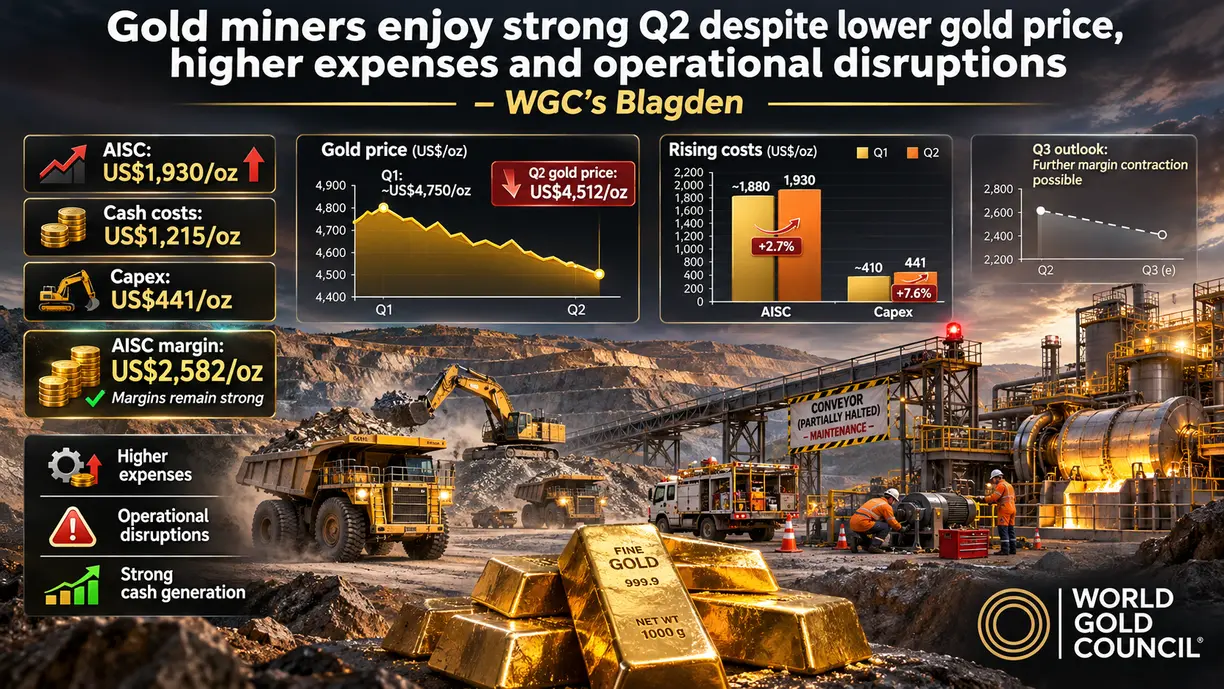
(Kitco News) – While the second quarter of the year saw gold prices pull back dramatically from the all-time highs of Q1, and rising expenses and operational disruptions ate into margins and profitability, gold miners still enjoyed an excellent Q2 by annual and historical measures, according to a new analysis by Oliver Blagden, Mine Supply Analyst at Metals Focus on behalf of the World Gold Council (WGC).
After seeing an exceptional first quarter in 2026, Blagden wrote that lower gold prices combined with increased costs to put miners’ margins under additional pressure.
“Global average gold producer All-In Sustaining Costs (AISC) rose by 8% q/q and 22% y/y to a record US$1,930/oz,” he noted. “This marked the 29th consecutive year-on-year increase, underlining the persistence of cost pressures. Higher sustaining capital expenditure, operating expenses and production disruption outweighed lower royalties, although strong cash generation continued to support investment, shareholder returns and resilient balance sheets.”
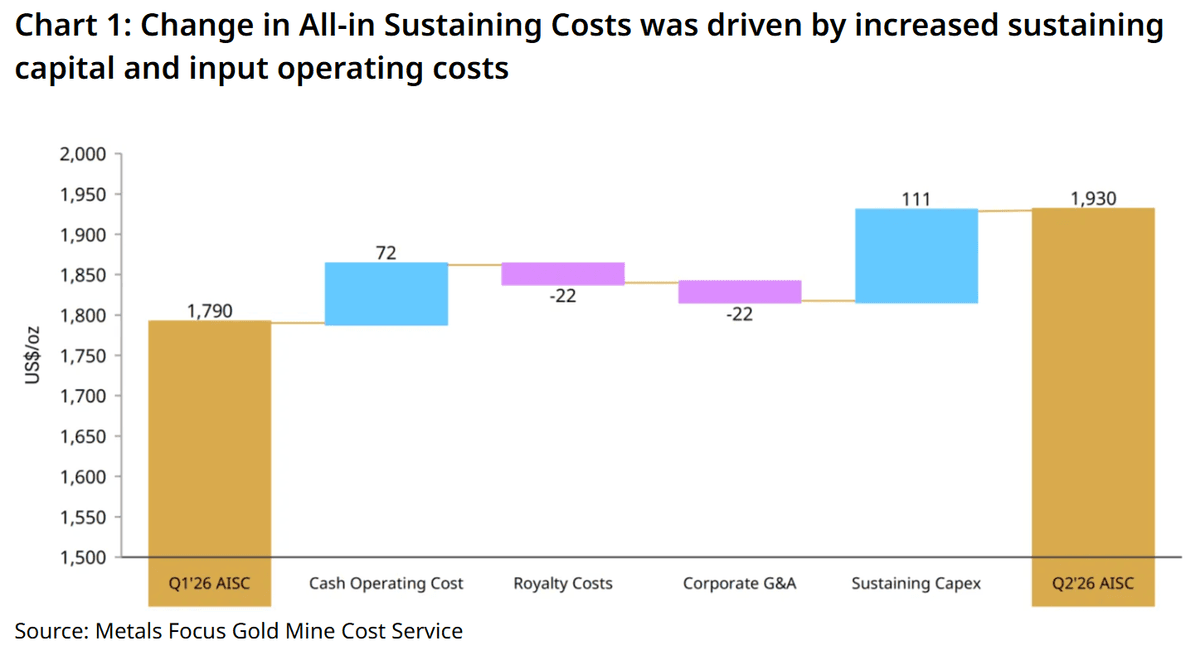
Q2 also saw sustaining capex replace royalties as the principal driver of higher AISC, with capex rising 34% from Q1 and 25% year over year to a record-level $441/oz. “The increase was equivalent to around 80% of the US$139/oz q/q net rise in AISC, lifting sustaining capital’s share of the industry’s cost base to 23%, from 18% in Q1’26,” Blagden said. “However, spending increases were concentrated in a minority of operations rather than being uniform across the industry.”
He noted a number of operational disruptions at major mines which contributed to these costs, but said despite these disruptions “production at the operations covered by Metals Focus’ Gold Mine Cost Service recovered by 1.6% q/q and average grades improved by 1.4%.”
“However, on an annual basis, output and grade were lower, by 4.4% and 3.1% y/y respectively,” he added. “Costs therefore rose despite a modest quarterly recovery in output, highlighting the impact of increased expenditure alongside localised operational setbacks.”
Blagden also highlighted the continued rise of onsite operating expenses. “Cash Operating Costs rose by 6% q/q and 18% y/y to US$1,215/oz, while Total Cash Costs increased by 4% q/q and 22% y/y to US$1,406/oz,” he said. “Labour and fuel remained important pressures.”
And supply-chain constraints affected not only the cost, but also the availability of essential inputs. “Delays in obtaining consumables or mobilising equipment can restrict activity, while more expensive supplies raised expenditure on the work that continued,” he noted. “Meanwhile, lower gold prices provided partial support through lower royalties. Average royalty and production-tax costs fell by 11% q/q to US$185/oz, although they remained 53% higher y/y. Their share of AISC eased to 9.6%, from 11.6% in Q1’26.”
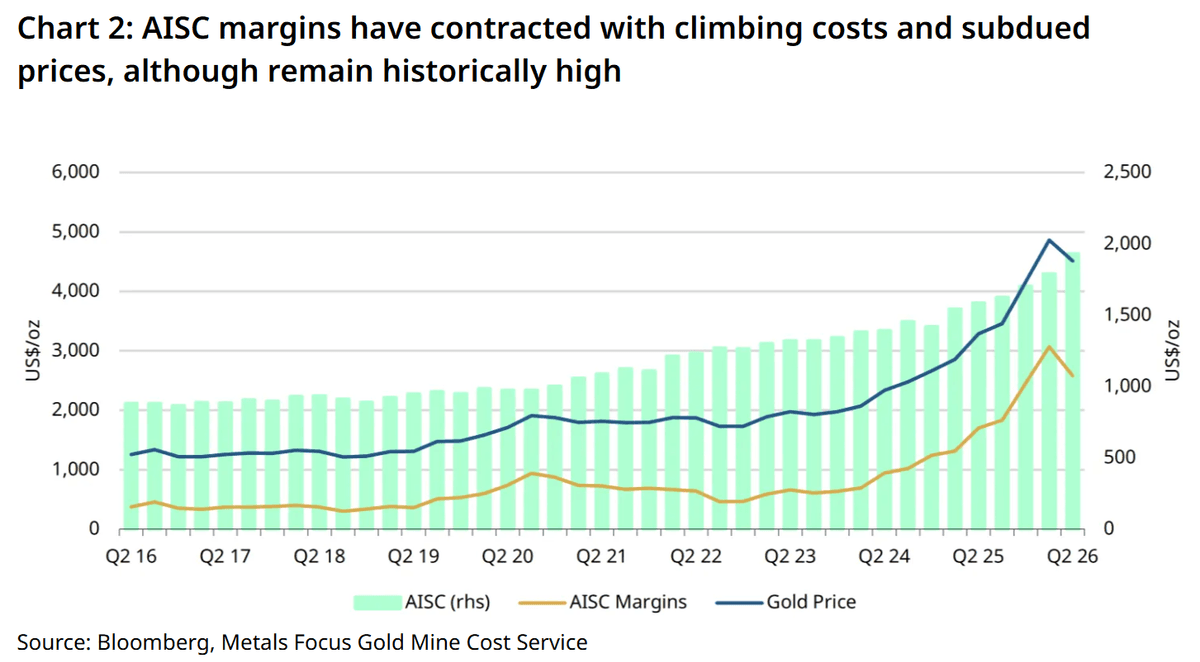
But even as miners’ margins were lower than the sky-high ones from Q1, the sector’s cash generation remained strong.
“Higher costs coincided with a 7.2% q/q decline in the average gold price to US$4,512/oz,” Blagden wrote. “Consequently, average AISC margins contracted by 16% q/q to US$2,582/oz, reversing part of the exceptional expansion seen in Q1’26. Nevertheless, gold prices remained 37% higher y/y, and margins were up by 52%. The average margin was still the second highest in our dataset, leaving miners with a substantial cushion despite the quarterly squeeze.”
Blagden characterized Q2 2026 as “a retreat from exceptional margins rather than a collapse in cash generation.”
“Gold prices remained high by historical standards and miners’ balance sheets remained robust,” he said. “As AISC approaches US$2,000/oz, expensive fuel purchases, continuing supply-chain and inflationary pressures are expected to sustain cost increases. Meanwhile, the gold price averaged US$4,266/oz in Q3’26, down by 5.5% q/q, and stood at around US$4,040/oz at the time of writing. Combined with rising costs, this sets the stage for further margin contraction over the remainder of 2026.”
“Looking ahead to 2027, a forecast recovery in gold prices would lift royalty costs, but this should be more than offset through higher revenues, supporting wider margins and further strengthening miners’ financial positions.”
See live precious metals prices for gold, silver, platinum and palladium — in USD, CAD and 12 more currencies.
