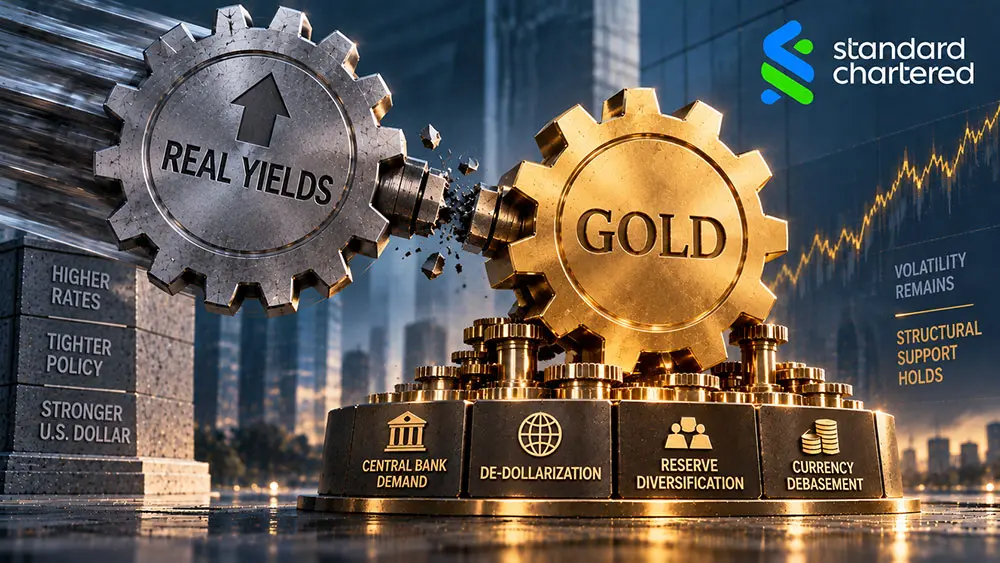
(Kitco News) - Gold’s traditional relationship with real interest rates is weakening, and while higher U.S. rates and a potentially stronger U.S. dollar could keep prices volatile in the near term, Standard Chartered sees structural forces providing a solid floor under the precious metal.
In her latest precious metals report, Suki Cooper, Global Head of Commodities Research at Standard Chartered Bank, noted that gold has already recovered from its losses following the Federal Reserve’s 25-basis-point rate hike last week and is looking for technical support around its 50-day moving average.
Cooper said the market’s focus appears to be shifting away from short-term monetary policy toward broader concerns surrounding de-dollarization, currency debasement and the risk of market intervention. While gold remains volatile, she said official-sector demand continues to provide consistent downside support and that structural drivers remain in place to push prices higher, although potentially at a slower pace.
Looking ahead, Standard Chartered sees gold prices averaging around $4,650 an ounce in the final quarter of the year. Spot gold prices are currently averaging around $4,350 an ounce in the third quarter.
As part of its expected year-end recovery, Cooper said she sees evidence that the metal is becoming less sensitive to rising real yields.
“Correlations with 10Y and 30Y yields are nearing neutral territory, at -20% and -10%, respectively. While correlations with 2Y and 5Y real yields have also weakened,” she said. “While correlations with 2Y and 5Y real yields have also weakened (to -16% and -22% from -30% and -38% a month ago, respectively), they remain meaningful.”
Cooper explained that the shift in the global marketplace is significant considering how dramatically monetary policy expectations have changed this year. At the start of 2026, markets were pricing in two Federal Reserve rate cuts while gold traded around $4,500 an ounce. Gold is now trading only modestly below that level despite the Fed having raised rates and markets expecting another hike before year-end.
Standard Chartered said gold investment demand is showing renewed momentum even as bond yields remain elevated.
Gold-backed exchange-traded product holdings are on track to match August’s strong inflows. August inflows totaled 121 tonnes, the highest monthly level since September 2025. Cooper noted that inflows have continued even as 10-year nominal Treasury yields breached 5%, highlighting the growing importance of gold’s longer-term structural drivers.
Meanwhile, speculative positioning does not appear excessively crowded.
Ahead of the September Federal Reserve meeting, tactical investors reduced their exposure primarily through profit-taking. Net fund length fell by 11,800 contracts during the preceding two weeks, the largest decline since March, while gross longs dropped by 14,000 contracts.
Cooper noted that Standard Chartered’s economists expect the Federal Reserve to raise rates one more time in December and then keep monetary policy unchanged through 2027. The bank has also raised its yield forecasts across the curve following a 50-basis-point upward revision to its terminal Fed rate forecast.
Despite the bullish year-end outlook, Cooper said gold still faces some potential headwinds. She said the U.S. dollar could represent a more important near-term risk for gold than real yields.
She noted that gold’s three-month rolling inverse correlation with the U.S. dollar remains around 54%, significantly stronger than its current relationship with real rates.
Standard Chartered noted that the September rate hike may have eased some concerns surrounding currency debasement while improving the dollar’s relative yield advantage. The bank is therefore watching for further U.S. dollar strength, which could create a near-term headwind for gold. (Kitco Global Index shows how much of today's gold move is the dollar versus the gold market itself.)
However, Cooper noted that investors had already positioned for a high probability of a rate hike before the Fed meeting, helping explain why the subsequent bout of profit-taking was relatively short-lived. Net fund length remains firmly positive at 34% of open interest, but Standard Chartered does not consider positioning overcrowded.
“Tactical positioning tends to price in rate hikes faster than rate cuts, limiting downside after the rate hike,” she said.
See live precious metals prices for gold, silver, platinum and palladium — in USD, CAD and 12 more currencies.
