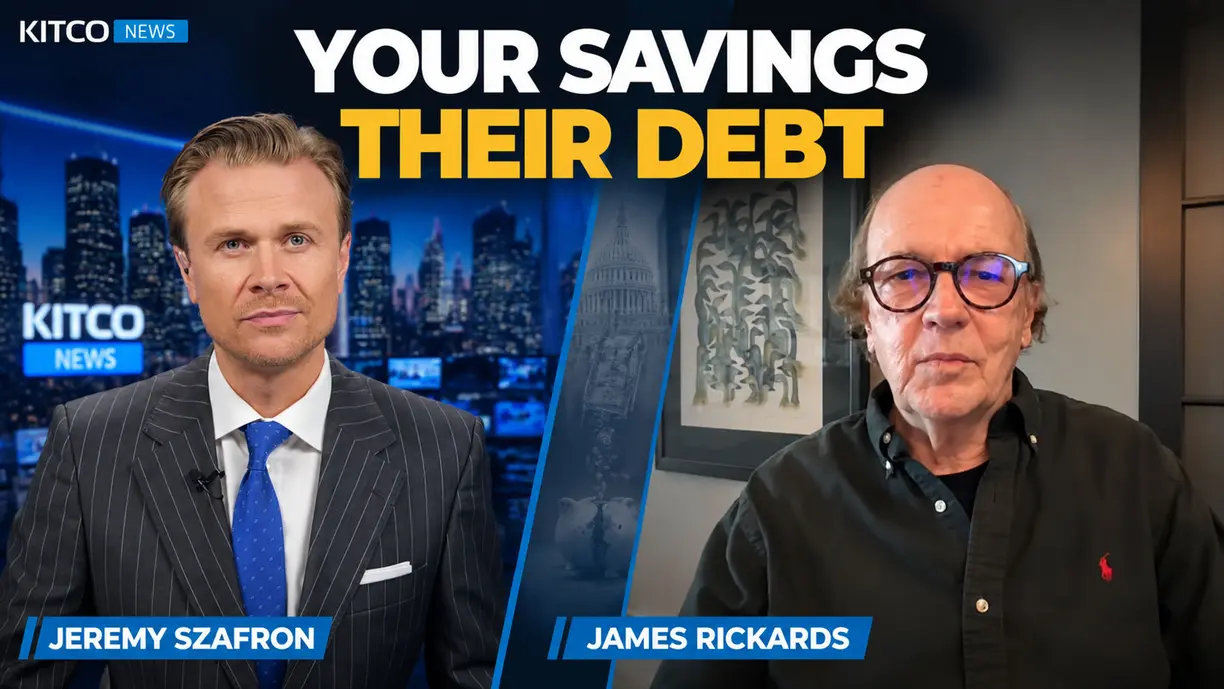
(Kitco News) - With the 10-year Treasury yield at a 2002 high, the author of "Currency Wars" says inflation, not repayment, is how the debt gets handled, and he thinks gold has already shown savers where to hide.
The U.S. government owes more than $40 trillion, and it now spends about $1 trillion a year just on interest. Jim Rickards doesn't think anyone in Washington plans to pay it back.
"You don't have to pay off the national debt. We're not going to pay off the national debt," Rickards told Kitco News. "What you have to do is roll it over at a reasonable interest rate."
That's getting harder. On Thursday, the 10-year Treasury yield touched 5.34%, the highest since 2002, as the global bond selloff picked up speed. Britain's 30-year yield crossed 6% for the first time since 1998, and a Bloomberg index of government debt just had its worst quarter since 2024. Every tick higher makes Washington's debt more expensive to roll over, and the Congressional Budget Office already expects net interest costs of roughly $1 trillion this fiscal year.
Rickards, a lawyer and author who has advised the U.S. intelligence community on financial threats, thinks the real way out isn't repayment or spending cuts. It's inflation. And he says the bill goes to anyone holding dollars. His answer is hard assets, and he points to Russia's gold as proof they work.
How a debt shrinks without anyone paying it
He points to what happened after World War II. Federal debt peaked at about 118% of GDP in 1946 and fell to about 31% by 1981, according to St. Louis Fed data. The debt itself never stopped growing. What changed was the size of the economy in current dollars, and a lot of that growth was rising prices.
"It wasn't the debt. The debt went up three times. And it wasn't the deficit," Rickards said. "What grew was the GDP. But when you're talking about debt, you're not talking about real GDP. You're talking about nominal GDP. Nominal GDP is real GDP plus inflation."
For a borrower as big as the U.S. government, he said, that's the whole point. "Inflation favors the debtor," Rickards said. "If you're the debtor, you love inflation because you owe the same nominal amount of dollars, but they're worth less. It's like, 'Hey, here's your trillion dollars back. Good luck buying a loaf of bread.' Who's the biggest debtor in the world? It's the United States of America."
The Fed, for its part, says it's fighting inflation, not welcoming it. It raised rates in September for the first time since 2023, and Chair Kevin Warsh said inflation had been "too high ... for too long." Rickards' argument is that over decades, the math of the debt wins out over the promises.
Savers are already feeling it
You can see the squeeze in the household numbers. Americans boosted inflation-adjusted spending by 0.6% in August, the biggest jump since March 2025. But their inflation-adjusted income didn't grow at all, and the saving rate slipped to 4.1%, the lowest since 2022, according to the Bureau of Economic Analysis.
Rickards says inflation doesn't need to be dramatic to do real damage. "3% inflation cuts the value of the dollar in half in about 24 years," he said. Stretch that over a 48-year career and three-quarters of it is gone. "If you start talking 4 or 5% inflation, forget it. Your dollar is like an ice cube melting in your hand."
Retirees have it the worst, he said, because their raises always arrive after prices have already moved. "Social Security gets adjusted every year, but that's after the fact," Rickards said. "Any increase in Social Security payments in 2027 will be based on 2026 inflation. So you're always slightly behind the curve."
"The victims are the people who don't have assets," he said, "or people on fixed incomes of various kinds where they can't make the adjustment."
What Russia's frozen reserves taught gold owners
For Rickards, the best case for gold came in 2022, when Western governments froze roughly $300 billion of Russia's reserves held abroad. The gold Moscow kept at home was the one thing they couldn't touch.
"Russia made more than $150 billion in mark-to-market profits on the gold," he said. "One, the U.S. couldn't get their hands on it. Two, it went up on fears and concerns that the U.S. Treasury might steal your Treasury securities. And Russia made a fortune on their gold, so it did exactly what it was supposed to do."
The numbers back him up. Russia's central bank held about 73.2 million ounces of gold as of Aug. 1, according to Kitco News reporting. At roughly $1,900 an ounce in early 2022 and about $4,160 now, those holdings are worth around $165 billion more.
Gold hit a record $5,589.38 an ounce on Jan. 28 and was trading near $4,158 on Thursday. That's still higher than the roughly $3,866 it sold for a year ago. Rickards doesn't expect central banks to power the next big run, but he thinks they limit the losses. "It's not going to cause the spikes," he said. "But what it does do, it establishes a floor." He calls that "an asymmetric trade," where "your downside is limited because central banks are always there, buying and putting a floor under it."
Just make sure it's actually gold. "If you own gold futures or unallocated gold contracts or options on gold or ETFs, you don't own gold," he said. "You have a contract."
A softer inflation number, but don't call it relief
Wall Street got some good news this week. Core PCE, the Fed's favorite inflation gauge, rose 0.2% in August and 3.0% from a year earlier, cooler than the 3.3% economists expected. Odds of another rate hike in October dropped to 34.9% on Wednesday from 70.9% a week earlier, according to CME FedWatch.
Rickards expects the Fed to hold when it meets Oct. 27–28. "At the October meeting they're going to stand pat," he said. December is a different story: "they'll probably raise it then."
And he isn't buying the idea that inflation is beaten. "If inflation goes from 3.7% to 3.4%, the New York Times will say inflation came down," he said. "Prices didn't come down. All it means is that your prices are still going up, but they're going up at a slower pace." Prices are still well above where they were before the 2022 surge, when annual inflation peaked at 9.1%, according to the Bureau of Labor Statistics.
China, Japan and a world that's short on dollars
China's holdings of U.S. Treasuries have dropped to $618 billion, the lowest since 2008, according to Treasury data. Many investors read that as Beijing walking away from the dollar. Rickards sees the opposite.
"They're doing it because they're desperate for dollars," he said. "It's not because they're getting out of dollars. They wish they had more dollars." In his view, China needs the cash to prop up the yuan and to shore up banks sitting on bad dollar loans. "It's actually a sign of a global dollar shortage and a Chinese weakness rather than any weakness on the part of the United States."
Meanwhile, China keeps buying gold. The People's Bank of China reported 2,387 tonnes in August, its 22nd monthly increase in a row, according to China's State Administration of Foreign Exchange and the World Gold Council. Central banks around the world have bought roughly 1,000 tonnes a year for four years, the WGC data show.
Japan is adding pressure too. Its 10-year bond yield hit 3% last month for the first time since 1996, which threatens the trade where investors borrow cheaply in yen and invest the money abroad. Rickards expects smart money to try to "get out of this trade before the stampede begins." Treasury Secretary Scott Bessent has described U.S. support for Japan's currency by saying, "I am the house now." Rickards isn't convinced. "The house is not the Treasury, it's the market," he said.
The next round of inflation is already on its way
Rickards thinks the next push higher in prices is coming from energy. The diesel crack spread, the gap between crude oil and refined diesel, hit a record of about $110 a barrel in September. JPMorgan estimates Middle East crude exports are back to 98% of pre-war levels, but refined fuels are at just 58%.
A tanker of oil you could get delivered right now is "running $130, $140 a barrel," Rickards said, well above Brent futures near $100 on Thursday. "Every single thing you buy arrives by truck at some stage, and trucks run on diesel," he said. "Higher diesel prices mean higher prices for everything you buy."
His advice is the same approach he says got him through the 1970s. "You own real estate, gold, silver. You own various kinds of hard assets," Rickards said. "Even as your dollars are worth less, your assets are going up, and that's how you survive."
Watch the full interview above, where Rickards explains whether Washington could ever freeze Americans' gold, and shares the one piece of money advice he gives his own kids. For more conversations like this, subscribe to Kitco News on YouTube.
────────────────────
SPONSORED BY KALSHI
Trade the first CFTC-regulated gold and silver perpetuals in the U.S., 24/7, with no expiration date.