(Kitco News) – Next Wednesday’s September CPI report will likely be in line with expectations, with the hotter August print an outlier, and the Federal Reserve may have already delivered the only hike of the current cycle, according to Natixis.
“We expect the September CPI report to show a 0.19% increase in the core component and 0.6% for the headline,” economists Christopher Hodge and Selin Aker wrote in Natixis’ October CPI Preview. “August CPI came in above consensus expectations due to a rise in components that we don’t think will be repeated.”
The economists expect a core print “that is indicative of a gradually normalizing inflation trajectory.”
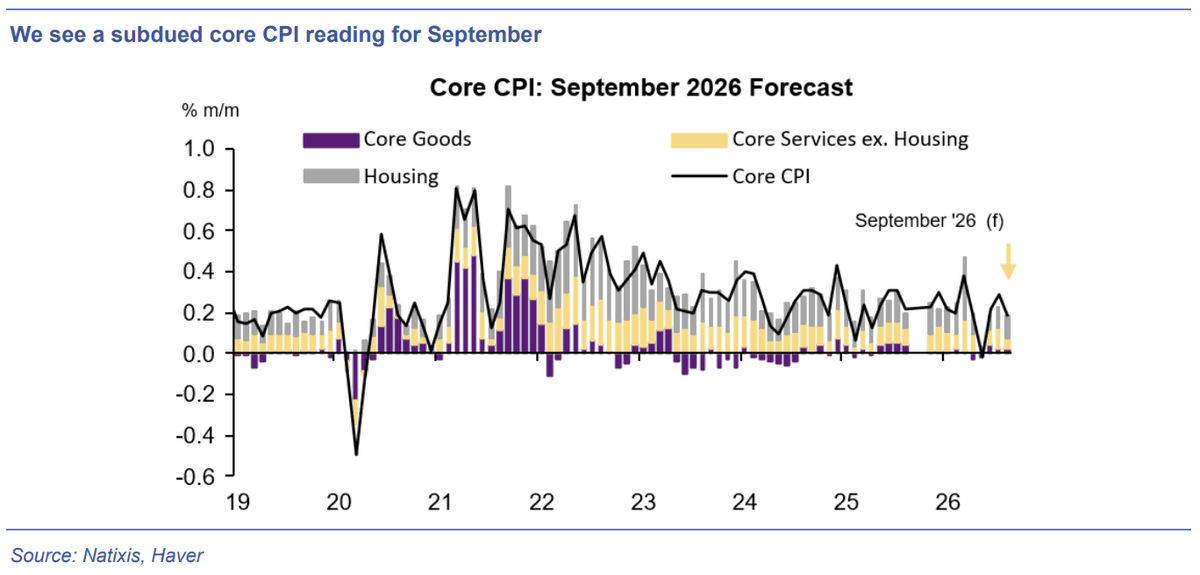
“If our forecast is accurate, core inflation on the year should remain stable at 2.4%, while the 3m annualized rate would increase to 2.8% (as the negative print from July would drop out of the equation), and the 6m annualized rate would fall a hair to 2.55%,” they added.
Natixis believes the recent acceleration in headline inflation is largely driven by energy and food prices, and is not evidence of a renewed broadening in underlying inflation. “We continue to think that inflation breadth is improving, albeit in fits and starts, and that supply shocks are not bleeding through more broadly to core prices,” they said.
Hodge and Aker also analyzed price pressures according to some alternative metrics, which paint a more moderate picture.
“’Underlying inflation’ has been cited frequently by Fed Chair Kevin Warsh, and while this concept has typically been used as shorthand for core inflation, Warsh has alluded to alternative measures, such as trimmed mean and median inflation,” they said.
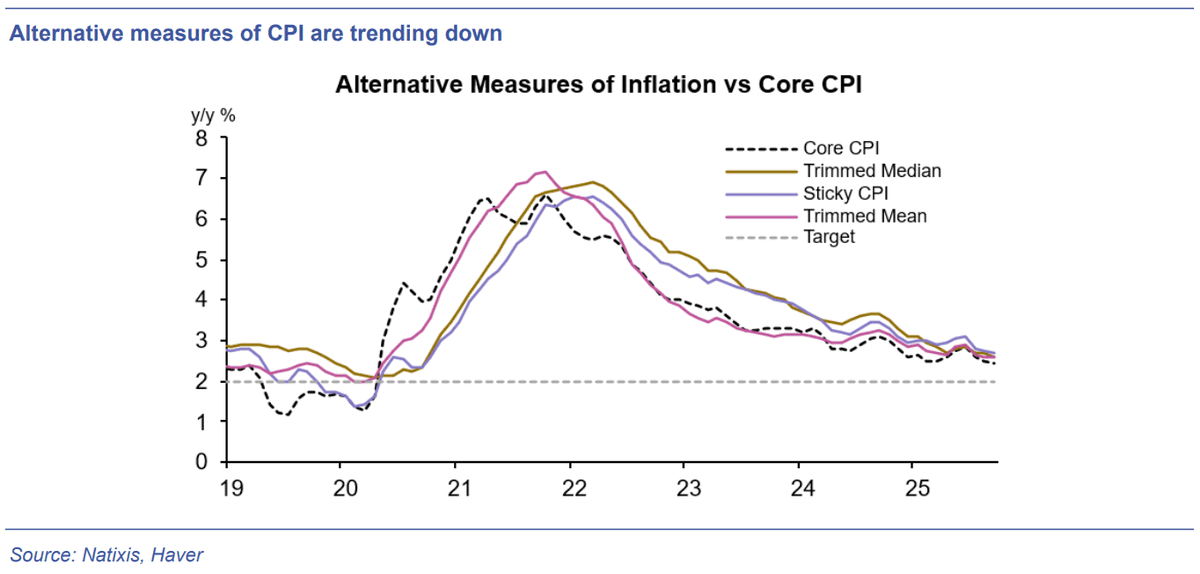
“According to the metrics compiled by various regional banks, there has been an improvement in the inflation trend, though not fully back down to the Fed’s target of 2%,” the economists noted. “The Fed’s task force on inflation will likely use some of these alternative measures to see if they should play a more prominent role in assessing the trajectory of inflation.”
“Warsh has also mentioned the breadth of inflation and cited the number of subcomponents running above 3%. Breadth is a useful gauge for monetary policymakers,” they added. “It can help distinguish if price pressures are concentrated in just a few areas, whether or not those areas can be addressed with monetary policy, and if those pressures are bleeding into the broader inflation complex.”
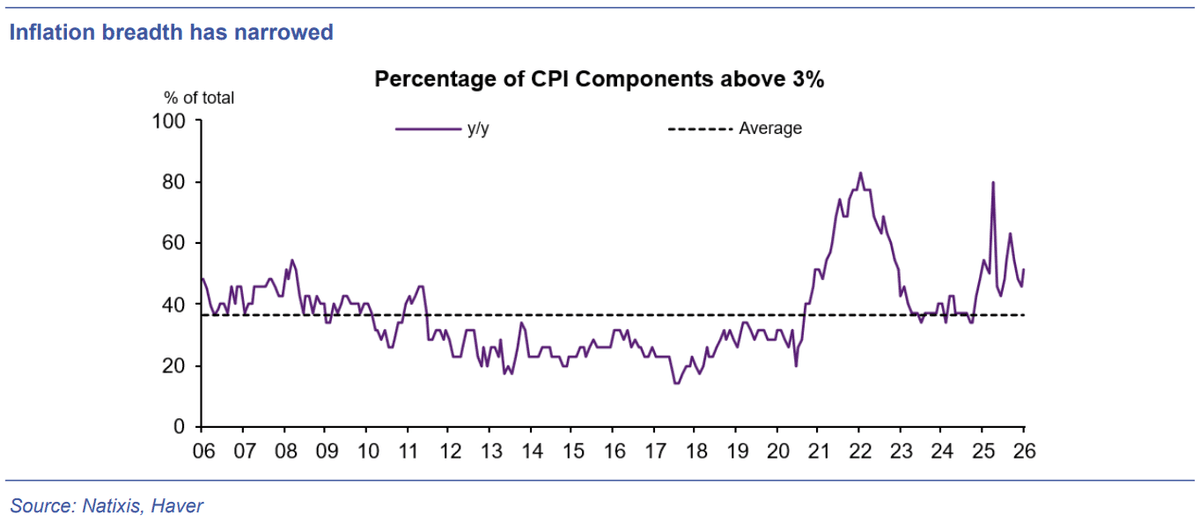
“As we can see from the above chart, the trajectory of inflation breadth was improving until the second half of 2025 when the effects of the ‘Liberation Day’ tariffs began to take effect,” they said. “Another supply-induced bump to price levels was to be expected from the energy shock following the commencement of the Iran War.”
Turning to the near-term implications for Federal Reserve monetary policy, Hodge and Aker wrote that August’s downbeat CPI report didn’t dent their optimism about the inflation trajectory, and they continue to expect inflation to decline over the coming quarters.
“With the Fed, in our view, disproportionately calibrating its reaction function based on incoming data, subsequent inflation prints will be its lodestar,” they said. “Because we think those data will be encouraging, it is quite possible that September was the lone hike of the cycle. That would be unusual, though. Usually when the Fed feels the need to hike rates, they will typically do it multiple times to really tamp down price pressures. But this is not a typical cycle. The broader trajectory of inflation is still intact, it’s just that the process is not happening fast enough and therefore the Fed feels that a nudge — via just one adjustment higher to the policy rate — could be helpful.”
Hodge and Aker expect the Fed to hold rates unchanged at the late October meeting, “as will it allow time to further assess economic variables by the December meeting, as well as avoid the political fallout from hiking just before mid-term elections in early November.”
“The Fed, in our view, will remain fixated on incoming data prints though and as the last CPI report shows us, month-to-month data can be noisy and it is difficult to string together a series of better prints,” they concluded. “For that reason, we will pencil in another hike in December or January as well as a tweak to the policy rate may be all that the policymakers think is needed to nudge inflation lower.”
