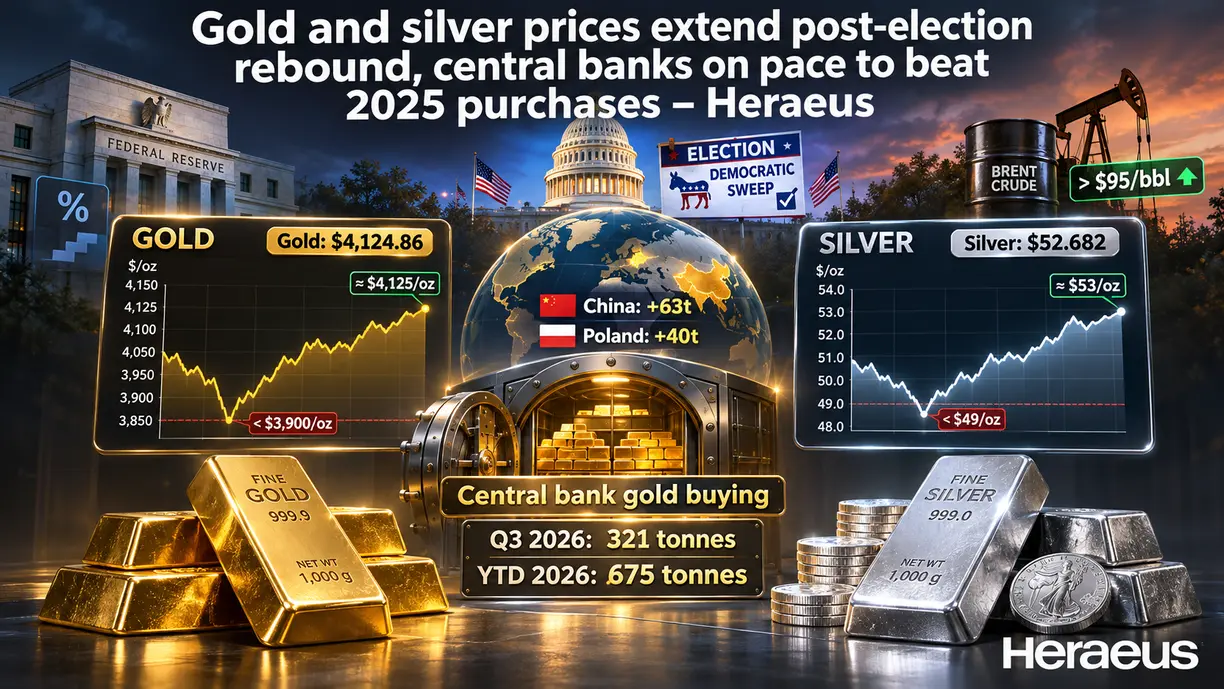
(Kitco News) – Gold and silver are continuing to build on last week’s strong rally following the Democratic sweep of the midterm elections, but the precious metals will likely face pressure from resurgent oil prices and elevated Fed rate expectations, according to analysts at Heraeus.
In their latest update, the analysts noted that gold prices saw a sharp rebound last week soon after dropping to a fresh 2026 low.
“Having fallen by more than 15% from its late-August high, the price briefly dropped below $3,900/oz, breaking the June low near $3,950/oz,” they wrote. “The Democrats’ sweep of both houses of Congress then triggered gold’s largest daily gain since August, and the price recovered above $4,000/oz.”
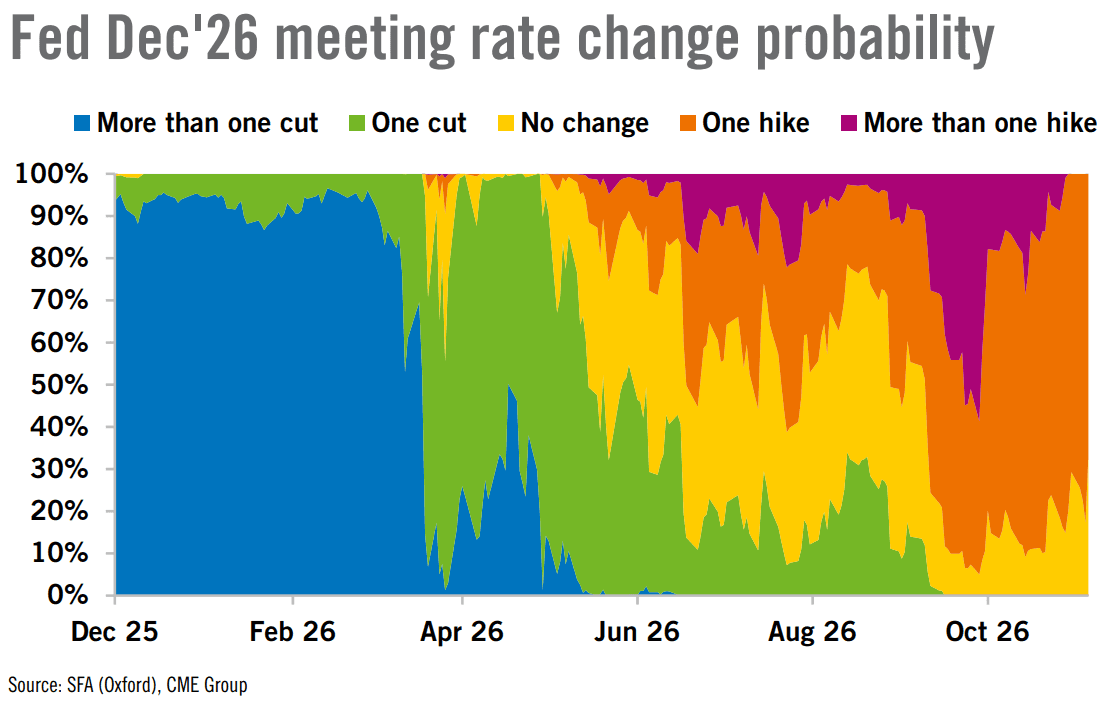
Meanwhile, Brent crude prices fell nearly 9% in a single session on the expectation that the new Democrat-controlled Congress would hasten the end of the Iran war. “However, the conflict is ongoing and Brent prices are already recovering above $95/bbl, and the new Congress does not sit until January,” the analysts said. “Fed policy, meanwhile, remains a headwind: Friday’s non-farm payrolls report came in at 165,000 against expectations of 65,000, strengthening the case for another rate increase in December. The markets are now pricing in around a 79% probability of a December hike.”
Heraeus noted that central bank gold purchases accelerated in Q3, pushing year-to-date buying above last year’s pace.
“The World Gold Council estimates that central banks and other official institutions added 321 tonnes in Q3, 42% more than a year earlier and well above the five-year quarterly average of 227 tonnes,” they said. “This boosted purchases during the first nine months of 2026 to 675 tonnes, 6% ahead of the same period last year. However, only 120 tonnes of Q3 buying was identified in reported country-level data. China and Poland dominated disclosed purchases, adding 63 tonnes and 40 tonnes respectively, while Kazakhstan and Uzbekistan each added 14 tonnes.”
“The stronger buying in Q2 and Q3 coincided with some moderation in the gold price from its Q1 peak, although the continued accumulation at historically high prices suggests strategic reserve diversification remains the principal driver.”
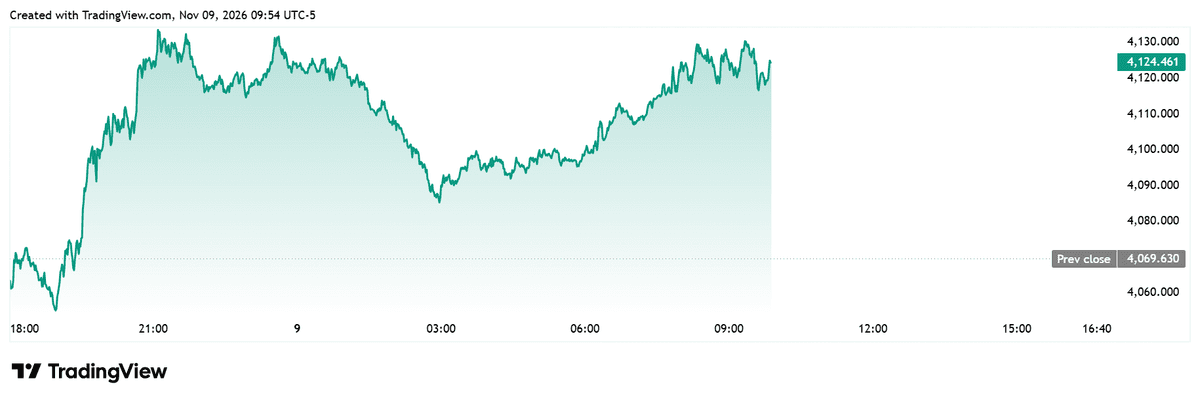
Spot gold continued to flirt with session highs on Monday morning, and last traded at $4,124.86 per ounce for a gain of 1.30% on the daily chart.
Turning to silver, Heraeus analysts wrote that while Hecla’s silver output was consistent with last year’s third-quarter numbers, the largest primary silver producer in the U.S. and Canada is still behind its 2025 pace.
“Hecla’s silver production was broadly stable quarter-on-quarter in Q3’26, although output remained below last year’s level,” they said. “The company produced 4.17 moz of silver, little changed from 4.21 moz in Q2’26 but 9% lower than the 4.58 moz produced a year earlier. Lower yield at Greens Creek and Lucky Friday was largely offset by record output from Keno Hill, where production increased by 54% quarter-on-quarter to 963 koz as the milled grade improved significantly.”
“At 16.1 moz, Hecla would account for around 1.9% of global silver mine supply, which is forecast at 844.1 moz in 2026,” they added.
The analysts also noted the strength in silver prices last week after the gray metal set its own 2026 low.
“The price fell below $50/oz to a new year-to-date low just below $49/oz, before rebounding above $52/oz,” they said. “However, silver remains well below the June/July range that contained its prior year-to-date low. The rebound has so far recovered only a small part of the preceding decline.”
Silver prices were also not far from session highs on Monday, with the gray metal trading close to $53 per ounce early in the equity session.
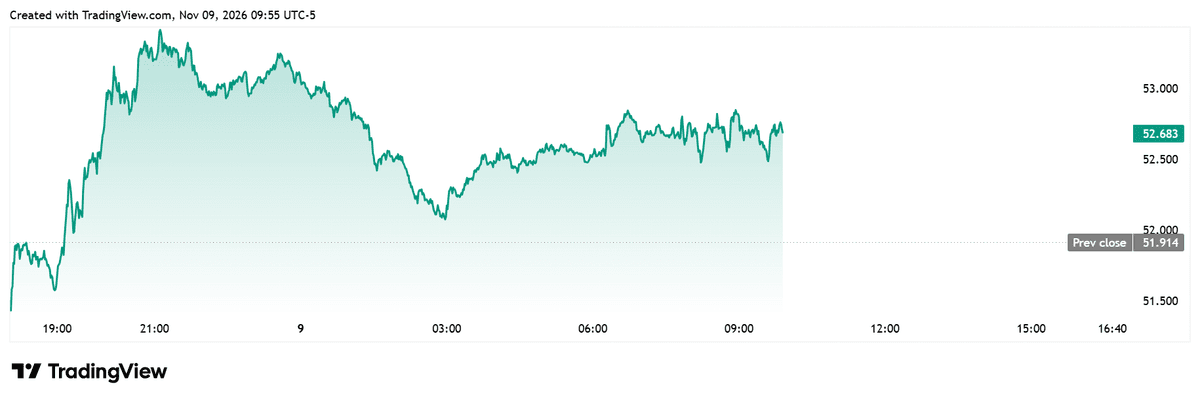
Spot silver last traded at $52.682 per ounce for a gain of 1.48% on the daily chart.
See live precious metals prices for gold, silver, platinum and palladium — in USD, CAD and 12 more currencies.
